A Shelf With a Return Date: Running Tool Loans From the Trade Counter
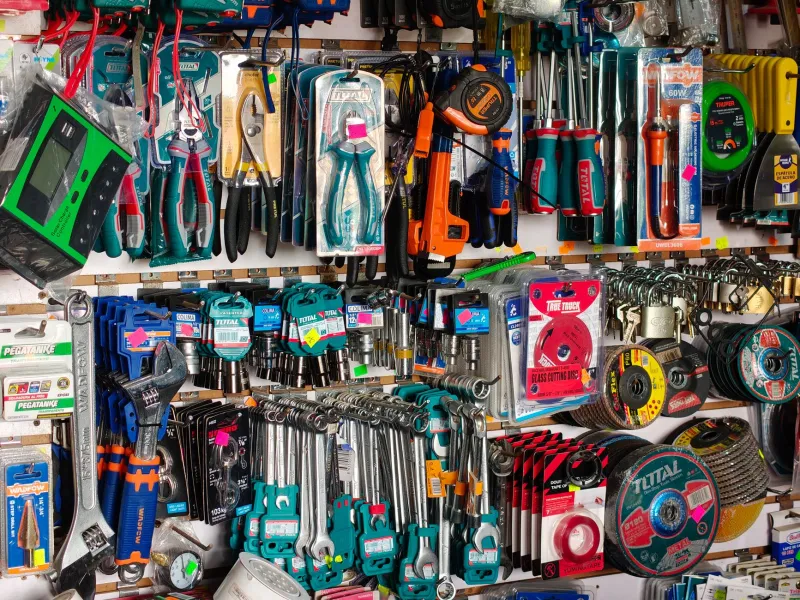
A tool loan scheme is one of those ideas that sounds generous until the third customer of the day walks off with a demo drill and no clear return date. Then it becomes a stock-control problem with a crocodile clip attached.
But the idea itself is sound. Trade customers often hesitate over a tool because they cannot tell from a box whether it will suit the job in front of them. A short, controlled loan can settle that question far better than a leaflet. It also builds the kind of counter relationship where people come back because you helped them make a decision, not because you had the cheapest sticker in the window.
The trick is to treat the loan shelf as a small service operation, not a lending library. A shelf with a return date, a named owner and a simple log will earn its space. A loose arrangement based on good intentions will cost you stock, time and goodwill.
Start with a shelf, not a lending library
Pick one bay or one locked cupboard and make it the loan shelf. Keep it separate from sale stock. This sounds obvious, but plenty of counters blur the line when things get busy: a boxed item goes out as a favour, comes back marked, and suddenly it is neither new nor demo.
The cleanest approach is to use ex-demo units, supplier samples or a small number of deliberately designated loan tools. Give each one a serial number or a coloured asset tag. Write that number on the loan note, not just the product name. If you stock three similar cordless drills, “the Makita” is not a useful record.
Start small. One or two items is enough to test whether the scheme works for your customers. A dedicated loan shelf with four useful lines beats a cupboard full of odds and ends that nobody can find.
What earns a place on the shelf
The best loan tools are the ones where handling the item answers a real question. Fit, weight, balance, access and compatibility are all things a customer cannot properly judge through a cardboard box. A compact drill for tight loft work, a long-reach hedge trimmer, a specific battery platform or a specialist blade setup can all make sense as loan items if they are central to a genuine buying decision.
Be equally clear about what does not go out. Safety-critical PPE is a poor loan item for hygiene and liability reasons. Calibrated test equipment should not be passed around like a spare tape measure. Anything that needs complex setting up, software registration or a licence key is usually more trouble than it is worth. High-value kit with a ready resale market also deserves a hard no unless you have a very tight process and a deposit that matches the risk.
Consumables are not loan stock. If a customer needs a blade, a bit, a battery or a cartridge to test a tool, sell them the consumable. The loan is for the tool, not the whole job.
The paperwork that keeps it honest
You do not need a legal department to run this. You do need a consistent record. A simple loan card or a spreadsheet line should capture the customer’s name, business, phone number, the item and serial number, the date and time out, the agreed return date, and the condition on issue.
A photo on the phone at handover is quick and useful. It takes ten seconds and settles most arguments about whether a scuff was already there. If you take a deposit, make the terms clear before the tool leaves the counter: what it covers, when it is returned, and what happens if the item comes back damaged or late. Keep the wording plain and give the customer a copy.
One item per customer, a short loan window and a clear return time are sensible defaults. A weekend loan can work well for a Friday customer who wants to try a tool on a Saturday job, but it needs to be booked as a weekend loan, not an open-ended favour.
The handover and the comeback
The handover is where most loan schemes either work or fall apart. Show the customer the controls, the accessories and the case. Count the parts. Point out any existing marks. Confirm the return date out loud and write it on the card. That small ritual makes the loan feel professional rather than casual.
On return, give the item a proper ten-minute check before it goes back on the shelf. Clean it, test it, charge the battery if it takes one, and count the accessories again. Check for damage that goes beyond fair wear. A scratched housing from normal site use is one thing; a missing chuck key or a cracked casing is another.
Have a simple rule for late returns. A phone call on the day after the due date is usually enough. If lateness becomes a habit, stop lending to that customer. The scheme is there to support genuine buying decisions, not to subsidise a tool hire business.
Keep it from becoming a free hire desk
A loan shelf only earns its keep if it leads somewhere. Track what goes out and whether it turns into a sale, a repeat visit or at least a clearer answer for the customer. If a line goes out repeatedly and never converts, ask why. It may be the wrong product, the wrong customer or the wrong loan window.
Review the shelf every month or two. Remove the lines that create work without helping sales. Keep the ones that settle real questions. A controlled loan scheme should feel like an extension of good counter service: short, logged, useful and returned in a condition that still reflects well on the business.